You have several bank accounts, a life insurance policy, perhaps some shares in SCPI, and a savings account. Checking each client space separately to see where you stand takes time, and the overall picture remains unclear. Digital wealth management tools address this specific problem: bringing all your assets onto one screen and helping you make more informed investment decisions.
Online Fraud and Security: The Filter to Apply Before Choosing Any Tool
Before entrusting your financial data to a platform, one reflex is essential: verify its reliability. Competitors rarely discuss this topic, yet it is the primary selection criterion. The European regulation DORA now imposes enhanced management of IT risks, incident reporting, and increased control of their technology service providers on financial actors.
For an individual, this concretely means that you must check the establishment’s approvals and its security procedures before opening an account. Consult the AMF blacklist, which lists several thousand fraudulent sites. In 2025, fraud through social manipulation reached 516 million euros and accounted for over 40% of the total amount of payment fraud, according to the Payment Security Observatory.
The threat does not only come from technical vulnerabilities. It mainly comes from phone calls from fake advisors or targeted ads on social media. Never validate a transfer during an incoming call, even if your interlocutor mentions your name and account number. No digital tool replaces this basic vigilance.
Platforms like Investory allow you to centralize the monitoring of your wealth while maintaining control over your investment choices, which limits exposure to unregulated intermediaries.
Wealth Aggregator: What the Consolidated View Changes in Your Decisions
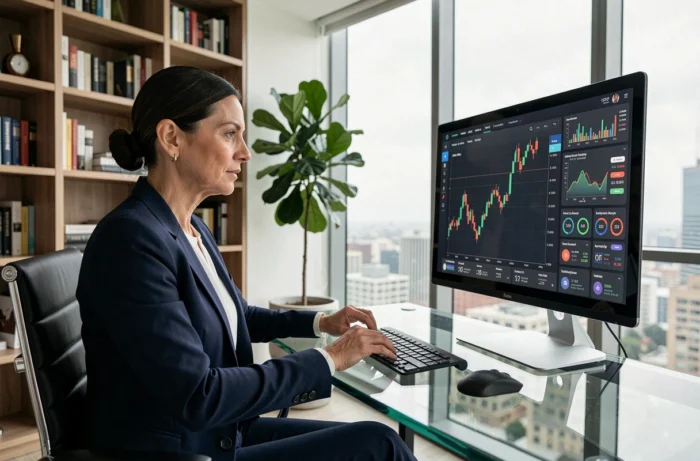
A wealth aggregator connects your various accounts (bank, life insurance, PEA, SCPI, real estate) and displays their value on a single dashboard. The benefit goes beyond visual comfort.
Have you ever noticed that your investment decisions change when you see all your assets side by side? The actual distribution of your wealth often surprises. Many individuals discover that they are overexposed to real estate or that their precautionary savings far exceed their actual needs.
The consolidated view reveals imbalances that fragmented monitoring conceals. From there, adjusting the allocation between financial assets, real estate, and cash becomes a concrete operation, not a vague intuition.
What a Good Aggregator Should Display
- The real-time valuation of each investment line, including SCPI shares and life insurance contracts in unit-linked accounts
- The allocation by asset class (real estate, stocks, bonds, cash) in graphical form to immediately spot imbalances
- The performance history net of fees, not just the gross performance displayed by each institution in its own client space
- Personalized alerts in case of significant variation or upcoming contractual deadlines
Investment Simulators: Going Beyond Mental Calculation
Online simulators allow you to test scenarios before committing your money. Let’s take a simple example: you’re hesitating between strengthening your life insurance in euro funds or buying SCPI shares. A wealth simulator will show you the impact on your taxes, expected return, and overall risk level.
A reliable simulator incorporates actual taxation, not just gross return. This is the difference between a useful tool and a marketing calculator. Ensure that the simulator takes into account your marginal tax rate, social contributions, and any advantages related to the holding period.
Why does this matter? Because two investments showing the same gross return can generate very different net incomes depending on your tax situation. The net return after taxes is the only indicator that reflects what you actually keep.
Artificial Intelligence and Wealth Advisory: What the Algorithm Cannot Replace
Robo-advisors offer automatic allocations based on your risk profile. They analyze your responses to a questionnaire and then adjust your portfolio’s allocation. For a beginner investor, this is a useful starting point.
The AMF and ESMA remind us that investment firms remain responsible for AI-assisted services, even when the algorithm contributes to preparing a decision. The tool does not transfer legal responsibility to the machine. Regulators also point out risks of bias in automated recommendations and misinformation.
An algorithm excels at rebalancing a portfolio according to predefined rules. It is less effective at integrating complex life parameters: a real estate project in three years, an anticipated inheritance, a change in marital status. These situations require human advice, possibly supported by data, but not replaced by it.
When the Digital Tool Suffices, When the Wealth Manager Intervenes
To monitor the performance of your investments, automatically rebalance, and receive alerts, a digital platform meets the need. As soon as your wealth involves rental real estate, transmission, or tax optimization over several years, a wealth management advisor provides an analysis that the algorithm does not produce.
The best use of digital tools is to arrive better prepared in front of a professional. You already know your allocation, your net performances, your weaknesses. The advice then becomes more targeted, quicker, and often less costly because the diagnosis is already established.
Digital wealth management does not oppose technology and human relationships. It redistributes roles: the tool processes data, the advisor processes decisions. Choosing regulated platforms, verifying approvals, and maintaining a critical eye on automated recommendations remains the best way to protect and grow your wealth.